Commercial insurance underwriting is built on one objective: understanding risk well enough to make informed, profitable decisions. Before an underwriter can determine whether to offer coverage, set pricing, or request additional information, they must first evaluate the quality and completeness of the submission in front of them.
The challenge is that modern commercial insurance submissions rarely arrive in a standardized format.
Applications often include ACORD forms, loss runs, schedules of values, supplemental questionnaires, broker emails, financial documents, inspection reports, and numerous supporting attachments. Important information may be spread across dozens or even hundreds of pages, requiring underwriters to spend valuable time locating, validating, and organizing key details before they can begin evaluating the actual risk.
This is why experienced underwriters focus on a handful of critical data points first.
These core pieces of information help determine whether a submission fits the carrier's appetite, whether additional review is required, and how the account should be prioritized within the underwriting workflow. They also provide the foundation for every subsequent underwriting decision, from pricing and coverage terms to referrals and risk selection.
As commercial insurance continues to become more data-driven, insurers are investing in technology that structures fragmented submission data into decision-ready intelligence. Rather than manually searching through multiple documents, underwriters increasingly rely on AI-powered underwriting workbenches to surface the most important information upfront, allowing them to spend less time gathering data and more time evaluating risk. Convr
Understanding which data points matter most helps explain not only how underwriting decisions are made, but also why clean, structured, and complete submission data has become such a competitive advantage for commercial insurers.
1. Business Classification Sets the Foundation
One of the first pieces of information an underwriter reviews is the applicant's business classification.
Understanding exactly what a company does provides immediate context for nearly every aspect of risk evaluation. A contractor, manufacturer, transportation company, retail business, and technology firm each present very different exposure profiles, even if they generate similar annual revenue.
Business classification influences underwriting guidelines, expected loss patterns, regulatory considerations, pricing models, inspection requirements, and available coverage options.
Unfortunately, this information is not always straightforward.
Applicants may describe their operations differently across applications, websites, broker submissions, and supplemental documentation. Some businesses perform multiple operations that introduce additional exposures, while others have evolved significantly since previous policy periods.
Accurately classifying a business early in the underwriting process allows carriers to quickly determine whether the submission aligns with their appetite and whether additional review is necessary before moving forward.
2. Loss History Provides Immediate Risk Context
Past claims remain one of the strongest indicators underwriters evaluate when assessing commercial risks.
Loss history helps answer several important questions.
Has the business experienced frequent claims? Were losses isolated incidents or part of an ongoing pattern? Have corrective actions been implemented? Are claim severities increasing over time? Do previous losses suggest operational issues that could affect future performance?
Loss runs also help underwriters distinguish between organizations with similar operations but very different risk characteristics.
Two construction companies may perform identical work, yet one consistently demonstrates strong risk management while the other experiences repeated workers' compensation or liability claims. Reviewing historical loss information helps identify those differences early in the evaluation process.
Because loss data often arrives in multiple formats from different carriers, structuring and normalizing this information is essential for efficient underwriting. Modern underwriting platforms increasingly automate this process, allowing underwriters to analyze trends rather than manually extracting claim information from lengthy documents. Convr
3. Revenue Helps Measure Exposure
Annual revenue is another critical data point reviewed early in the underwriting process.
Revenue often serves as a proxy for business size and operational complexity while influencing premium calculations across many commercial insurance products.
A business generating $2 million in annual revenue generally presents different exposure characteristics than one generating $200 million. Larger organizations may have more employees, additional locations, broader operations, larger customer bases, and more complex contractual relationships.
Revenue also helps underwriters identify inconsistencies elsewhere in the submission.
For example, reported payroll, employee counts, sales volumes, or operational descriptions that appear inconsistent with stated revenue may warrant additional questions before underwriting continues.
Accurate financial information supports more consistent pricing while helping carriers evaluate risk within the proper business context.
4. Exposure Details Shape the Underwriting Decision
After establishing the basic profile of the applicant, underwriters turn their attention to the specific exposures presented by the business.
These details vary by industry but often include information such as:
- Number and location of facilities
- Products manufactured or distributed
- Contractual relationships
These exposure details determine not only whether coverage is appropriate but also how policies should be structured and priced.
Incomplete or inconsistent exposure information frequently leads to follow-up questions that delay quoting and increase manual work for underwriting teams.
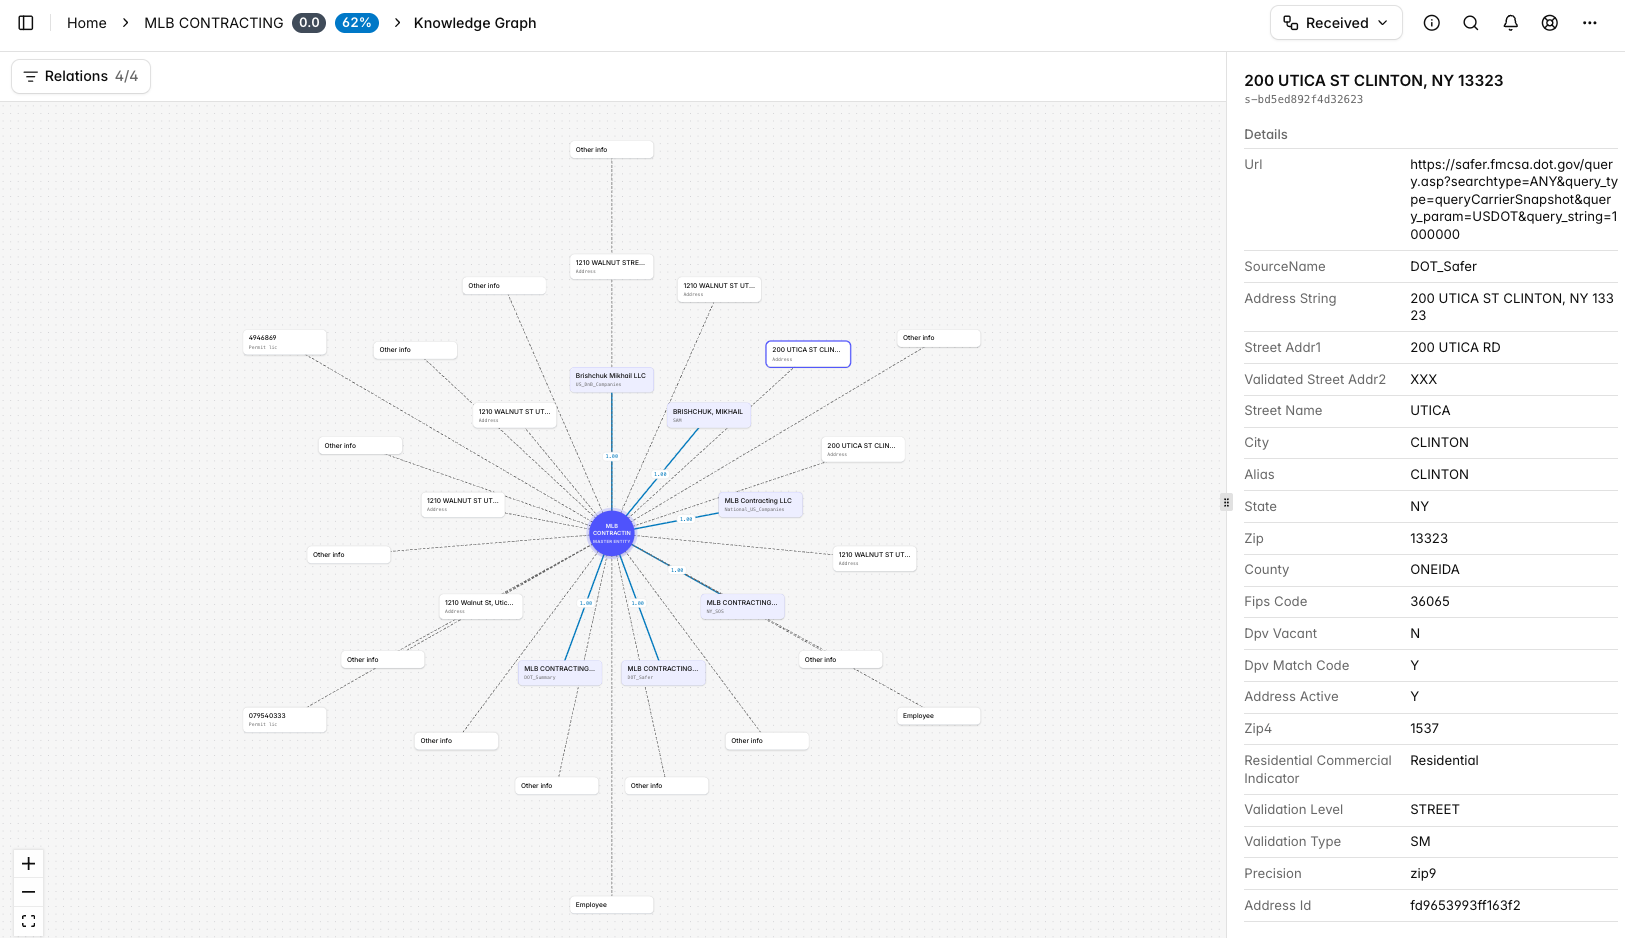
This is one reason insurers increasingly rely on AI-powered submission intake technology to extract, organize, and validate exposure information before underwriters begin their review. Convr's underwriting workbench, for example, structures fragmented submission data and enriches it with contextual risk intelligence so underwriters can evaluate exposures more quickly and consistently. Convr
5. Prior Coverage Helps Identify Gaps and Trends
Another important area underwriters review early is the applicant's insurance history.
Previous coverage provides valuable insight into how the business has managed its risk over time. Underwriters look for information such as current carriers, policy limits, deductibles, renewal dates, and any recent changes in coverage.
This information helps answer several important questions. Has the business maintained continuous insurance coverage? Have coverage limits changed significantly from one policy period to the next? Has the applicant moved between multiple insurers in a short period of time? Were there any coverage restrictions or cancellations that require further investigation?
Prior coverage also helps underwriters identify potential gaps that could affect both pricing and eligibility. For example, a business that has operated without certain types of coverage may present different underwriting considerations than one with a long history of comprehensive commercial insurance.
When this information is scattered across applications, declarations pages, broker correspondence, and policy documents, manually piecing it together can consume valuable underwriting time. Automated document intelligence helps organize this information into structured data, allowing underwriters to review coverage history much more efficiently.
Why Data Quality Matters as Much as the Data Itself
Even the most experienced underwriter can only make decisions based on the information available.
Incomplete applications, inconsistent documents, missing schedules, and conflicting data create unnecessary delays throughout the underwriting process. Instead of evaluating risk, underwriters spend time requesting clarification, searching through attachments, or following up with brokers for information that should have been readily available.
Poor data quality affects more than productivity.
Incomplete information can increase quote turnaround times, create inconsistent underwriting decisions, reduce broker satisfaction, and ultimately affect an insurer's ability to compete in today's commercial insurance market.
High-quality submissions, by contrast, allow underwriters to begin evaluating the account immediately. Structured, validated data improves consistency while reducing manual effort across the submission intake process.
As commercial insurance organizations continue investing in digital transformation, improving submission quality has become one of the most effective ways to increase underwriting efficiency without compromising decision quality.
How AI Is Changing the Way Underwriters Review Data
Artificial intelligence is not replacing underwriters. Instead, it is helping them spend more time applying their expertise where it creates the greatest value.
Historically, much of an underwriter's day involved administrative work. Reading lengthy submissions, locating missing information, manually entering data into underwriting systems, comparing documents, and identifying inconsistencies often consumed hours before actual risk evaluation could begin.
AI-powered underwriting platforms are changing that workflow.
Rather than expecting underwriters to search through dozens of documents, modern solutions automatically ingest submissions, classify documents, extract key data points, validate information across multiple sources, and present structured summaries that support faster decision making.
This allows underwriters to focus on evaluating complex risks, exercising professional judgment, collaborating with brokers, and making informed underwriting decisions instead of spending valuable time on repetitive manual tasks.
Convr's AI-powered underwriting platform is designed specifically to support this transformation by automating submission intake, extracting critical underwriting information, enriching data with external intelligence, and delivering structured insights that improve speed, consistency, and underwriting accuracy. By reducing administrative work, insurers can improve operational efficiency while creating a better experience for both underwriters and distribution partners.
Best Practices for Improving Underwriting Efficiency
Whether reviewing submissions manually or with AI support, several best practices consistently improve underwriting performance.
Start by ensuring submissions contain complete and consistent information before they enter the underwriting queue. Early validation reduces delays later in the process.
Standardize data wherever possible. Structured information allows underwriters to compare risks more consistently while reducing unnecessary interpretation between different document formats.
Prioritize the data points that have the greatest influence on underwriting decisions. Business classification, loss history, revenue, exposure information, and prior coverage provide the foundation for evaluating most commercial submissions.
Leverage technology to automate repetitive administrative tasks rather than replacing professional judgment. AI performs best when supporting experienced underwriters by delivering cleaner, better-organized information.
Finally, continue refining workflows as new technologies emerge. Commercial underwriting continues to evolve rapidly, and organizations that combine experienced underwriting professionals with intelligent automation are well positioned to improve both operational efficiency and decision quality.
Frequently Asked Questions
What information do underwriters review first?
Most commercial underwriters begin by reviewing the applicant's business classification, historical loss experience, annual revenue, operational exposures, and prior insurance coverage. These core data points provide the foundation for evaluating whether a risk fits the carrier's underwriting appetite and what additional review may be required.
Why is loss history so important in underwriting?
Loss history helps underwriters understand how a business has managed risk over time. Reviewing previous claims allows insurers to identify trends, evaluate claim frequency and severity, and determine whether past losses suggest operational issues that may affect future risk.
How does AI help commercial underwriters?
AI helps automate many of the manual tasks that traditionally consume underwriting time. Modern underwriting platforms can classify submission documents, extract structured data, validate information across multiple sources, identify inconsistencies, and present organized summaries that allow underwriters to focus on evaluating risk rather than gathering information.
What happens if submission data is incomplete?
Incomplete submissions often lead to additional questions, slower quote turnaround times, inconsistent underwriting decisions, and increased administrative work. Improving submission quality allows underwriters to begin evaluating risk more quickly while creating a better experience for brokers and policyholders.
Can AI replace commercial underwriters?
No. AI is designed to support underwriters rather than replace them. Experienced underwriters continue to make complex risk decisions, apply professional judgment, and evaluate unique business circumstances. AI improves efficiency by automating repetitive data collection and document processing, allowing underwriters to spend more time on higher-value decision making.
Transform Underwriting Data Into Faster Decisions
Every commercial insurance submission contains the information underwriters need to evaluate risk, but finding, organizing, and validating that information has traditionally required significant manual effort. As submission volumes increase and customer expectations continue to rise, insurers need better ways to surface critical underwriting data quickly without sacrificing accuracy.
Convr helps commercial insurers modernize underwriting by using AI to automate submission intake, extract structured data from complex documents, enrich underwriting intelligence, and deliver decision-ready information to underwriting teams. The result is faster turnaround times, greater consistency, improved operational efficiency, and more time for underwriters to focus on what matters most: making confident underwriting decisions.
If your organization is looking to streamline submission intake and empower underwriters with AI-driven data extraction and risk intelligence, explore how Convr can help transform your underwriting workflow.