August 25, 2026
CASE STUDY
August 25, 2026
xx min read

The Future of Commercial Insurance Underwriting Over the Next 5 Years

Commercial insurance underwriting is entering a period of fundamental change.

Between 2026 and 2031, underwriting teams will move beyond using technology primarily to store documents, calculate rates, and manage policies. The next generation of underwriting systems will actively organize submission data, identify relevant risk signals, recommend next steps, automate routine decisions, and give underwriters a continuously updated view of each account.

This transformation will be driven by a practical business need.

Commercial submissions continue to arrive through emails, applications, spreadsheets, loss runs, statements of values, inspection reports, financial documents, and broker-created forms. Underwriters often have the information they need, but it is fragmented across documents and systems that do not communicate effectively.

Before evaluating the risk, the underwriter must locate the correct files, identify missing information, interpret inconsistent descriptions, reenter data, compare external sources, and determine whether the submission fits the carrier’s appetite.

That operating model is becoming increasingly difficult to sustain.

Brokers expect faster responses. Carriers want better risk selection. Underwriting leaders need greater consistency. Operations teams need to manage rising submission volumes without increasing administrative headcount at the same rate.

The future of underwriting will therefore be defined by how effectively insurers convert fragmented data into decision-ready intelligence.

AI will play a central role, but the goal will not be to remove underwriters from the process. The goal will be to give them better information, reduce repetitive work, and enable more consistent decisions across the underwriting lifecycle.

1. AI-Assisted Decisioning Will Become Part of Daily Underwriting

The first major change will be the expansion of AI-assisted decisioning.

Many underwriting technologies currently help users find documents, extract fields, or summarize submissions. Over the next five years, AI will move further into the decision workflow.

An underwriter reviewing a commercial account will increasingly be able to ask questions such as:

  • Does this risk fit our appetite?
  • What information is missing?
  • Which exposures require further review?
  • How has the account changed since the previous policy period?
  • Are the reported operations consistent with the business classification?
  • Which losses are most relevant to the current coverage?
  • What follow-up questions should be sent to the broker?

The system will not simply retrieve isolated data points. It will interpret information within the context of the account, the carrier’s underwriting rules, historical records, and relevant external risk signals.

This is an important distinction.

A general-purpose AI tool may be able to summarize a document, but commercial underwriting requires an understanding of relationships. Locations must be connected to property values. Vehicles must be connected to drivers and operating territories. Losses must be associated with the correct coverage period. Business descriptions must be interpreted within the context of classification, appetite, and exposure.

Future underwriting systems will become more valuable as they become more capable of preserving these relationships.

AI-assisted decisioning will also improve consistency. Instead of relying on each underwriter to manually locate the same information and interpret it in a different way, teams will begin with a more standardized risk view. Underwriters will still exercise professional judgment, but they will work from a more complete and reliable foundation.

2. Automated Submission Intake Will Become the Default

Submission intake is likely to experience one of the most visible transformations.

Today, many commercial underwriting teams still receive submissions through shared inboxes. Employees open messages, download attachments, identify document types, create records, extract information, and route the account to the correct team.

Over the next five years, much of this process will become automated.

Intelligent intake systems will be expected to:

  • Ingest submissions from email, portals, APIs, and other channels
  • Separate combined document packages
  • Classify applications, loss runs, schedules, and supporting files
  • Extract relevant underwriting information
  • Standardize data into a consistent schema
  • Identify missing or conflicting information
  • Check the submission against appetite rules
  • Route the account to the appropriate workflow
  • Create tasks or broker requests automatically

The result will be a significant change in the underwriter’s starting point.

Instead of opening an email containing a collection of raw attachments, the underwriter will open an account that has already been structured, summarized, enriched, and prioritized.

This does not mean every submission will move through without review. Commercial insurance documents are too varied, and many risks are too complex, for completely unattended processing in every situation.

The more realistic future is selective automation.

Straightforward, high-confidence tasks will be completed automatically. Ambiguous information, conflicting values, and unusual exposures will be routed to the appropriate person for review. Human attention will be directed toward exceptions rather than routine data entry.

3. Embedded Risk Intelligence Will Replace Manual Research

Underwriters frequently rely on information that does not appear in the original submission.

They may need to verify business operations, review location characteristics, investigate ownership, examine financial indicators, identify regulatory issues, compare industry classifications, or understand the risk environment surrounding a property.

This research is often completed through separate websites, third-party databases, internal systems, and manual searches.

The future underwriting workflow will bring that intelligence directly into the account.

Relevant external information will be embedded alongside the submission rather than presented as a disconnected data feed. The system will connect external signals to the appropriate business, location, exposure, or policy period so the underwriter can understand why the information matters.

For example, property intelligence should not simply provide a collection of location attributes. It should identify which characteristics may affect the relevant coverage and present those insights in the context of the submission.

The same principle applies to business data.

An external classification, revenue estimate, ownership record, or operational description becomes more useful when it is compared with the applicant’s information and used to identify a potential inconsistency.

Embedded risk intelligence will reduce the amount of time underwriters spend moving between systems. More importantly, it will make external data easier to interpret and apply consistently.

4. Real-Time Enrichment Will Create a Living View of Risk

Traditional underwriting often relies on a snapshot of the applicant at a particular moment.

The submission describes the organization when the application was completed, but commercial risks can change throughout the policy period. Businesses open new locations, change operations, purchase equipment, experience losses, adjust staffing, expand into new territories, or encounter new financial pressures.

Over the next five years, risk profiles will become more dynamic.

Underwriting platforms will increasingly enrich account data throughout the lifecycle rather than only during initial submission review. New information will be compared with historical data to identify material changes before renewal or when additional review is required.

This will give carriers a more continuous view of risk.

Instead of reconstructing the account from the beginning at each renewal, underwriters will be able to see what has changed, why the change matters, and which areas deserve attention.

Real-time enrichment will also improve prioritization. Accounts with meaningful changes can be routed for deeper review, while stable renewals may move through a more streamlined workflow.

The future of underwriting will therefore be less dependent on isolated annual evaluations and more focused on maintaining an evolving, contextual understanding of the insured risk.

5. Underwriting Workbenches Will Become the Operational Layer

Most insurers are unlikely to replace every core system within the next five years.

Policy administration platforms, rating engines, document repositories, data providers, CRM systems, and broker portals will continue to play important roles. The challenge will be connecting those technologies into a usable underwriting experience.

This is where the underwriting workbench will become increasingly important.

Rather than forcing underwriters to move between multiple applications, the workbench will act as an operational layer across the existing technology environment. It will bring together submissions, structured data, risk intelligence, tasks, appetite rules, communications, and decision support within a unified workflow.

The most effective workbenches will not attempt to become another isolated system. They will integrate with the insurer’s existing architecture and allow information to flow between intake, underwriting, rating, policy administration, and portfolio management.

For underwriters, the experience should become simpler even as the technology behind it becomes more sophisticated.

They will spend less time searching for information, reentering data, and tracking tasks manually. They will spend more time interpreting complex exposures, communicating with brokers, evaluating terms, and making decisions that require professional judgment.

That shift will form the foundation for the increasingly autonomous underwriting workflows discussed in the second half of this article.

6. Autonomous Workflows Will Handle More Routine Underwriting Tasks

The next stage of underwriting modernization will move beyond individual automation features toward increasingly autonomous workflows.

Today, many systems automate isolated tasks such as extracting fields from documents or routing submissions to the correct queue. Over the next five years, AI agents will begin coordinating several steps across the underwriting process.

For a straightforward submission, an autonomous workflow may be able to collect documents, classify the risk, identify missing information, enrich the account with external data, apply appetite rules, create a preliminary risk summary, and recommend the next action.

The system may then route the account based on confidence and complexity.

A high-confidence submission that falls clearly outside appetite could be declined or referred according to predefined rules. A complete, lower-complexity risk may move directly to rating or an accelerated review. An unusual account with conflicting information would be escalated to an experienced underwriter.

This approach will allow carriers to apply human expertise more deliberately.

Underwriters will not need to review every routine task with the same level of attention. Instead, they will focus on exceptions, complex exposures, large accounts, unusual coverage requests, and situations where professional judgment materially affects the outcome.

Autonomous workflows will require careful governance. Insurers will need clear authority limits, transparent decision logic, reliable audit records, and appropriate human review. The objective should not be automation without oversight. It should be controlled automation that improves speed while preserving underwriting discipline.

7. The Underwriter’s Role Will Become More Strategic

As technology handles more document processing and administrative work, the role of the underwriter will evolve.

Underwriters will spend less time locating data and more time interpreting it.

Their value will increasingly come from understanding complex exposures, identifying emerging risks, negotiating terms, managing broker relationships, and making decisions that cannot be reduced to a simple rule.

This shift will also change the skills insurers prioritize.

Future underwriters will need strong commercial judgment, but they will also need to understand how to work effectively with AI-generated insights. They must know when to trust an automated recommendation, when to question it, and when additional investigation is required.

Data literacy will become more important. Underwriters will need to interpret confidence levels, identify possible data quality problems, and understand how external information influences the risk assessment.

Communication skills will remain essential.

Even the most advanced underwriting platform cannot replace the relationship between carriers and brokers. Complex accounts often require discussion, negotiation, and an understanding of the insured’s broader business strategy.

Technology will strengthen the underwriter’s role by providing better preparation for those conversations.

8. Portfolio Intelligence Will Influence Individual Decisions

Underwriting has traditionally focused heavily on evaluating one submission at a time.

Over the next five years, individual account decisions will become more closely connected to portfolio-level intelligence.

Underwriters will be able to see how a proposed risk affects concentrations across industries, locations, property characteristics, coverage types, and emerging exposure categories. This information will help carriers understand not only whether a single account is acceptable, but also how it fits within the existing book of business.

For example, an account may appear attractive on its own but create additional concentration within a region exposed to severe weather. Another submission may support diversification by adding a well-managed risk in an industry where the carrier wants to grow.

AI-supported portfolio analysis will help underwriting teams identify these relationships earlier.

Leaders will also gain greater visibility into submission flow, appetite alignment, referral patterns, quote ratios, processing time, and the reasons accounts are accepted or declined.

This intelligence can improve capacity allocation, product strategy, distribution planning, and underwriting guidelines.

The result will be a closer connection between front-line decisions and broader portfolio objectives.

9. Explainability and Governance Will Become Essential

As AI becomes more involved in underwriting, insurers will need to understand how recommendations and decisions are produced.

A system that generates a risk score without showing the underlying information will have limited value in complex commercial underwriting.

Underwriters need to know which data points influenced a recommendation, where that information came from, whether it conflicts with the submission, and how confident the system is in its interpretation.

Explainability supports better decisions because it allows the underwriter to challenge or validate the output.

It is also important for governance.

Insurers will need documented controls governing data sources, model performance, user permissions, decision authority, referrals, and human oversight. They will need audit trails showing which information was reviewed, which recommendations were generated, and who made the final decision.

Governance should be designed into the workflow rather than added after implementation.

Organizations that establish strong controls early will be better positioned to expand automation confidently while maintaining regulatory compliance, underwriting consistency, and trust among employees and distribution partners.

10. Modernization Will Become a Business Strategy, Not an IT Project

The insurers that gain the most value from underwriting technology will treat modernization as an operating model change rather than a software installation.

Automating an inefficient process without redesigning it often produces limited improvement.

Carriers must first identify where underwriters lose time, which decisions require professional judgment, which routine tasks can be standardized, and how information should move between teams and systems.

Technology can then support the redesigned workflow.

Executive sponsorship will be critical. Underwriting, operations, technology, data, compliance, and distribution teams will need shared objectives and a clear understanding of how success will be measured.

Useful performance measures may include:

  • Submission processing time
  • Time to first underwriter review
  • Quote turnaround time
  • Percentage of submissions within appetite
  • Manual data entry reduction
  • Referral frequency
  • Quote and bind ratios
  • Underwriter capacity
  • Data completeness and accuracy

Successful modernization will also require adoption from the people who use the technology every day.

Underwriters should understand how new tools improve their work, where human judgment remains central, and how feedback will be used to refine the system.

The future of underwriting will not be created by technology alone. It will be created by insurers that combine capable platforms with redesigned workflows, experienced professionals, and clear strategic priorities.

Frequently Asked Questions

What will commercial insurance underwriting look like in five years?

Commercial underwriting will become more automated, connected, and data-driven. AI will organize submissions, extract and validate information, enrich accounts with external intelligence, and recommend next steps. Underwriters will remain responsible for complex decisions, negotiations, and professional judgment.

Will autonomous underwriting replace human underwriters?

Autonomous workflows will handle more routine tasks and lower-complexity submissions, but they are unlikely to replace experienced commercial underwriters. Complex risks require interpretation, negotiation, market knowledge, and an understanding of circumstances that automated rules may not fully capture.

What is AI-assisted underwriting?

AI-assisted underwriting uses artificial intelligence to support activities such as document classification, data extraction, risk enrichment, appetite screening, submission summarization, and decision support. The technology prepares and organizes information so underwriters can make faster and more informed decisions.

How will real-time data change underwriting?

Real-time enrichment will give carriers a more current view of an insured’s operations, locations, exposures, and financial condition. It can help identify material changes during the policy lifecycle and allow underwriting teams to prioritize accounts that require closer review.

What should insurers modernize first?

Many insurers begin with submission intake because it contains large amounts of manual, repetitive work. Automating document classification, data extraction, validation, and routing can create immediate efficiency while establishing the structured data needed for more advanced decision support.

Build the Underwriting Operation of the Future

Over the next five years, commercial underwriting will move from fragmented, document-heavy processes toward connected workflows built around decision-ready intelligence.

AI-assisted decisioning, automated submission intake, embedded risk data, real-time enrichment, and autonomous workflows will help carriers respond faster while applying underwriting expertise more effectively.

The competitive advantage will not come from automation alone. It will come from combining technology with experienced underwriters, clear governance, connected systems, and a well-designed operating model.

Convr helps commercial insurers create that foundation through an AI-powered underwriting workbench that transforms unstructured submissions into organized, enriched, and actionable risk intelligence. By automating intake and connecting critical underwriting information within a unified workflow, Convr enables teams to increase capacity, improve consistency, and make confident decisions faster.

Explore how Convr can support your underwriting modernization strategy and help your organization build a more intelligent, efficient, and connected commercial insurance operation.

‍

blogs

Keep Reading

More articles on AI, underwriting and the future of commercial P&C.

XX MIN READ

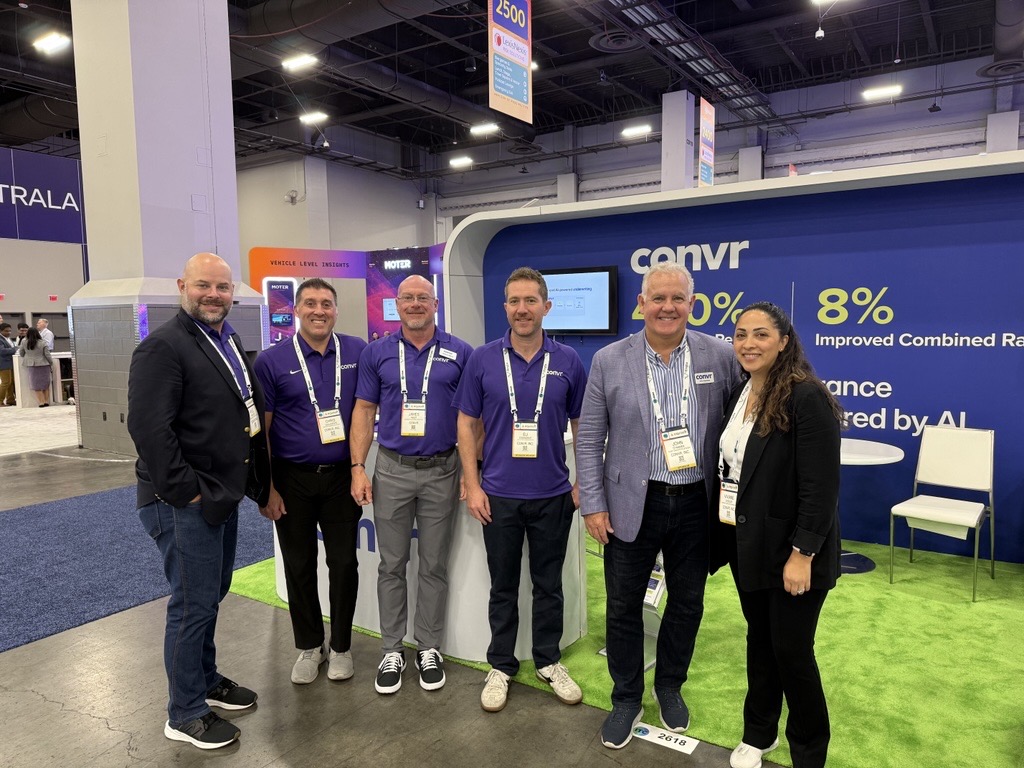
Convr at ITC Vegas 2026: A Recap of Insights, Innovation, and Connection

The intersection of insights and innovation... challenge and collaboration – that's what #teamconvr found this year at InsureTech Connect (ITC) Vegas 2026, held September 27 through October 1 at Mandalay Bay in Las Vegas, NV.

Like every year we attend the convention, it was busy, busy, and busy again, with demos, conversations, new agreements and presentations. If you walked the expo floor, you were sure to find Convr on both ends. Through it all, for Convr, this year's event sponsorship further confirmed our purpose and value in the commercial P&C insurance marketplace.  

Over the course of the event, Convr team members talked with hundreds of conference goers about the efficiencies and decisioning advancements our Convr AI Underwriting Workbench brings to commercial P&C carries, MGAs/MGUs, and brokers through the practical application of AI.

But if you missed us – with so many vendors and sessions competing for attention – we still want to give you a chance to get to know us and connect.

What we do

Convr is an AI underwriting workbench and data platform that digitizes and fuses submissions with the best available data sources to surface underwriting insights, business classification, and risk scores. At ITC Vegas, we met with some of the most tech-forward people in the industry, true professionals devoted to bettering the experience for insureds and the underwriting teams that help protect them.

That's exactly what Convr's AI Underwriting Workbench is built to do. Every day, our comprehensive workflow speeds the path from submission to quote by simplifying and expediting the underwriting process, improving the experience for both underwriters and their customers along the way. With the fast return on investment our platform delivers, ITC Vegas was the perfect stage for #teamconvr to share what we bring to the table.

We showed up in force. The Convr team took part in the Datos Insights Insurance Leaders' Summit panel on Tuesday, September 29, delivered a Mic Drop presentation on the Innovation and Solutions Stage on Wednesday, September 30, hosted private demos in #MR18, and welcomed a steady stream of visitors to our purple booth, #2618, on the main exhibit floor.

Thanks to everyone who stopped by. We're already looking forward to continuing the conversations, starting new ones, and seeing what the post-conference brings! Visit us here to meet with us or book a demo now.

‍

XX MIN READ

Build an Audit Trail Around Every AI-Assisted Decision

Explainability becomes much more valuable when it is preserved as part of the underwriting record.

For each material AI-assisted recommendation, carriers should be able to reconstruct:

  • What information was used
  • Which source documents supported it
  • Which underwriting rule or guideline applied
  • What recommendation was generated
  • Whether the underwriter accepted, changed or overrode it
  • When the decision was made

This creates an evidence trail that can support internal review, governance and audit.

It also gives underwriting leaders a clearer view of how AI is being used across the organization.

Track Rule and Guideline Changes Over Time

Underwriting guidelines change.

Authority levels move.

Appetite evolves.

Referral thresholds are updated.

An explainable system should preserve the version of the rule that applied when the decision was made.

Otherwise, a reviewer looking at the account months later may see a different rule from the one the underwriter actually used.

Versioning helps answer a simple but important question:

What did the system know and what rule was in force at that moment?

That level of traceability is essential when AI becomes embedded in real underwriting workflows.

Make Overrides Visible

Underwriters will sometimes disagree with an AI recommendation.

That is not a failure.

Commercial insurance is full of exceptions, nuance and context that may justify a different decision.

The important thing is to capture the override.

A governed workflow can record:

  • The original AI recommendation
  • The evidence behind it
  • The underwriter's final decision
  • The reason for the override

That creates useful feedback for underwriting leaders and helps identify where rules, data or workflows may need improvement.

It also reinforces the role of AI as decision support rather than an unchallengeable authority.

Explainability Supports Better AI Governance

As AI use expands, carriers need confidence that underwriting decisions remain controlled.

Explainability supports that by making it easier to review:

  • How data entered the workflow
  • Which rules were applied
  • Where human approval was required
  • When exceptions occurred
  • Which decisions were automated
  • Which decisions were escalated

This gives governance teams a clearer view of how AI operates in practice.

Instead of relying on broad claims that a model is accurate, the carrier can inspect how individual underwriting recommendations were produced.

Avoid Black-Box Automation

The biggest risk in AI-assisted underwriting is not simply that a model could be wrong.

It is that the organization cannot tell why it was wrong.

A black-box recommendation creates operational friction because underwriters either have to trust it or recreate the analysis manually.

A traceable recommendation creates a better path.

The underwriter can review the inputs, inspect the evidence, understand the rule and decide whether the recommendation makes sense.

That is what turns AI from an isolated tool into part of a governed underwriting process.

Frequently Asked Questions

What Is Explainable AI in Underwriting?

Explainable AI connects an underwriting recommendation to the data, source documents and rules that produced it, so the underwriter can understand and verify the decision.

Why Is Source Traceability Important?

It lets underwriters confirm where a risk attribute came from and inspect the original evidence rather than relying only on an AI-generated output.

Does Explainable AI Replace Human Judgment?

No. It gives underwriters better context and evidence so they can review, accept, modify or override a recommendation with confidence.

How Can Carriers Make AI Decisions Auditable?

They can preserve source lineage, structured risk data, applied rules, rule versions, recommendations, human overrides and final decisions as part of the underwriting record.

Why Do Insurance Ontologies and Knowledge Graphs Matter?

They give AI a structured understanding of insurance concepts and relationships, helping the system connect risk data in a way that is more consistent and easier to explain.

Make AI-Assisted Underwriting More Transparent With Convr

AI delivers the most value when underwriters can trust the path behind the recommendation.

Convr helps commercial P&C carriers turn fragmented submission information into structured, connected underwriting intelligence through an insurance-specific ontology, knowledge graph and standardized risk schema.

That foundation helps create AI-assisted workflows where risk attributes can be traced back to source documents, recommendations can be tied to underwriting rules, and underwriters remain in control of the final decision.

The result is not just faster underwriting.

It is underwriting that is more transparent, reviewable and governed.

Explore Convr to see how traceable, explainable underwriting intelligence can help your team adopt AI without sacrificing the evidence, context and control that commercial underwriting requires.

‍

XX MIN READ

Agentic AI in Commercial Underwriting: The Next Era of Underwriting Modernization

Agentic AI in commercial underwriting uses AI systems to coordinate tasks toward a defined underwriting objective. Within approved boundaries, these systems can review submissions, gather risk information, apply configured criteria, and move work to the appropriate next step. Underwriters retain responsibility for decisions that require their judgment and authority.

For commercial property and casualty (P&C) carriers and managing general agents (MGAs), the opportunity is practical: reduce the work between receiving a submission and making an informed decision.

A single account can require document review, data validation, external research, appetite checks, and referral preparation. When underwriters coordinate every step manually, valuable time disappears into administration.

Agentic workflows can connect these activities so underwriters begin their review with better information and clearer priorities. The foundation is structured insurance data, relevant risk context, and controls that define what AI can do.

The Convr AI Underwriting Workbench brings submission processing, risk intelligence, and workflow capabilities together to support this approach to commercial underwriting modernization.

How Is Agentic AI Different From Underwriting Automation and Generative AI?

Traditional automation, generative AI, and agentic AI contribute different capabilities to underwriting modernization. They can work together within the same process.

Traditional underwriting automation follows predefined rules. For example, a workflow routes a submission to a senior underwriter when the requested limit exceeds an authority threshold. This works well when the condition and response are clearly defined.

Generative AI interprets or creates content. It can summarize a loss run, extract information from documents, or draft a referral note. A user or surrounding workflow determines how that output is used.

Agentic AI coordinates steps toward an objective. An agent may determine that reviewing loss information, checking a guideline, and preparing a referral are necessary before a submission can progress. It uses available tools and permitted actions to complete that sequence.

Consider the objective: prepare this submission for underwriting review.

An agentic workflow could check whether required documents are present, identify conflicting values, gather approved external information, and route the account when the configured conditions are met. If essential information is missing, it could pause and flag what needs attention.

The distinction is the ability to coordinate work around the objective while respecting the insurer's rules.

Where Can Agentic AI Improve Commercial Underwriting?

Strong use cases combine several related tasks, reliable information, and a clear point at which a human should review the result. Submission intake, triage, risk enrichment, referral preparation, and renewal review are useful starting points.

Submission Intake and Data Validation

Commercial submissions often include ACORD forms, statements of values, loss runs, spreadsheets, supplemental questionnaires, and broker correspondence. Relevant facts may appear in several documents, sometimes with different values.

An agentic intake workflow could identify the documents received, organize the information, and evaluate whether the submission is complete enough for the next stage.

For example, an application may list annual revenue that differs from a supplemental questionnaire. Simply extracting both figures leaves the underwriter to discover the discrepancy later. A coordinated workflow could flag the disagreement, preserve both sources, and request review before the figure is used downstream.

This gives underwriting teams a clearer starting point and reduces the risk of passing unresolved data problems into later decisions.

Submission Triage and Appetite Evaluation

Underwriting teams need to decide which opportunities deserve attention first. That requires more than sorting submissions by arrival time.

An agentic triage workflow can bring together characteristics such as business operations, geography, requested coverage, limits, and loss information. It can then evaluate the account against configured appetite and prioritization criteria.

The result might be a recommendation to proceed, request more information, or refer the submission for review.

A useful distinction is whether an account falls outside appetite or simply lacks enough information to assess it. An incomplete submission may still represent a strong opportunity. Good triage makes that uncertainty visible instead of treating missing information as a definitive underwriting answer.

Risk Enrichment and Loss Review

Commercial underwriting often requires context beyond the original application. Underwriters may need to investigate business activities, locations, classifications, property characteristics, or historical losses.

An agent can help coordinate approved research and connect the findings to the account being evaluated. The information must match the correct business, location, and period.

For loss review, a workflow could organize claim information, identify missing periods, summarize patterns, and flag issues for investigation. The underwriter then evaluates what those findings mean for the risk.

This approach makes research more useful because the supporting evidence remains connected to the underwriting question. It also helps prevent an apparently relevant result from being applied to the wrong entity or exposure.

Referral Preparation and Authority Checks

Referrals can involve substantial preparation before a senior underwriter is able to act. Someone must identify the trigger, locate the relevant guideline, gather supporting information, and explain the requested exception.

An agentic workflow could assemble that material and route it to the appropriate reviewer. For example, a requested limit outside an underwriter's authority could trigger a referral package containing the exposure details, requested terms, applicable threshold, and source documents.

Authority checks should use explicit business rules and permission controls. The agent should never infer that it can approve an exception because similar accounts were approved previously.

The benefit is a more complete handoff, with the required decision still assigned to the authorized person.

Renewal Review and Material Change Detection

At renewal, underwriters need to understand what has changed since the previous policy period.

An agentic workflow could compare current submission information with historical account data and identify changes in locations, operations, exposures, requested limits, or loss activity. It could then direct attention to changes that meet defined review criteria.

For example, a business that previously operated from one location may have added a warehouse. That change could require additional property information and a fresh review of the exposure.

Organizing the comparison helps underwriters focus their investigation. An account that appears unchanged still needs to follow the insurer's renewal requirements.

Why Does Agentic Underwriting Need Insurance-Specific Risk Context?

AI needs to understand how facts relate to the insured risk before those facts can support a useful action.

An address could represent a mailing address, corporate headquarters, insured property, or temporary job site. A revenue figure might apply to one subsidiary or an entire organization. A loss amount may refer to paid losses, reserves, or total incurred losses.

These distinctions influence how information should be interpreted. Extracting a value accurately is only part of the task; the system also needs to preserve its meaning.

Insurance-specific data structures help connect businesses, locations, exposures, coverages, limits, and losses. They give AI a more reliable basis for retrieving relevant information and applying the correct workflow.

Convr's Risk Context Engine uses commercial P&C insurance semantics, a structured schema, and a knowledge graph to preserve meaning and relationships across underwriting data. These capabilities support the insurance context behind its AI Underwriting Workbench. Explore Convr's data and AI foundation.

For underwriting leaders, the practical evaluation question is: can the system explain which risk a fact belongs to, where it came from, and why it matters?

What Role Does an AI Underwriting Workbench Play?

An AI underwriting workbench brings account information, insights, tasks, and collaboration into a shared environment. Agentic capabilities can help advance work within that environment, subject to the organization's rules and permissions.

This matters because underwriting delays often occur during handoffs. A document arrives, but nobody notices it. A referral is prepared, but ownership is unclear. An account is ready for review, but it remains in the wrong queue.

A useful workbench should make the current status, responsible person, outstanding requirements, and next action visible. It should also connect with the systems needed to complete the process.

Convr combines submission processing and risk intelligence with configurable workflow automation. Its Workflow capabilities include routing, escalation controls, activity trails, and human review points where users can correct or override AI-assisted actions. Explore Convr Workflow.

When evaluating a workbench, ask to see a representative submission move through the process. Include a missing document or conflicting value. That reveals how the system handles the exceptions that determine whether automation is useful in daily underwriting.

How Should Insurers Control Agentic Underwriting Workflows?

Insurers should define an agent's permitted information sources, actions, escalation conditions, and approval requirements before expanding its autonomy.

Different activities warrant different controls. Gathering approved data or creating an internal task may be suitable for automation. Pricing exceptions, complex coverage judgments, and decisions outside delegated authority require the appropriate human review.

Four controls deserve particular attention:

  • Approved information: Specify which documents, guidelines, internal records, and external sources the agent may use. Keep applicable rules current.
  • Action permissions: Define what the agent can recommend, prepare, or execute, and enforce those permissions in the connected systems.
  • Escalation conditions: Pause or refer work when information is missing, contradictory, outside scope, or insufficiently reliable.
  • Traceability: Record the evidence considered, applicable rule, action taken, and any human review or correction.

An AI model's stated confidence should not, by itself, authorize a consequential underwriting action. Confidence measures need to be evaluated against actual performance and combined with explicit rules and review requirements.

Controls should also account for change. A revised appetite rule, updated authority limit, or new document format may affect the workflow. Assign responsibility for reviewing these changes and checking that the system continues to behave as intended.

How Can Insurers Start With Agentic AI?

Start with a narrow workflow where the objective, evidence, and escalation path are easy to define. Submission completeness or referral preparation can provide a more manageable starting point than broad autonomous underwriting.

First, document the current process. Identify where people copy information, search for evidence, wait for another team, or repeat work. Establish a baseline for handling time and errors.

Next, define the outcome the agent should achieve. “Prepare a submission for review using these required documents and checks” is more actionable than “improve underwriting productivity.”

Then test the workflow against representative accounts, including incomplete submissions, conflicting information, unusual business descriptions, and cases outside authority. Evaluate whether it recognizes when to stop as carefully as whether it completes routine cases.

Finally, introduce the workflow with a named owner and a review process. Use underwriter corrections and observed performance to decide whether to expand its scope.

This gives carriers and MGAs a practical way to build confidence while preserving accountability for underwriting decisions.

Which Metrics Show Whether Agentic AI Is Working?

Measure whether the workflow improves the quality and efficiency of underwriting work. Useful indicators include:

  • Time from submission receipt to underwriting review.
  • Manual handling time per account.
  • Number of avoidable handoffs or repeated data entries.
  • Completeness and accuracy of required information.
  • Referral preparation and turnaround time.
  • Incorrect routing, missed exceptions, and human overrides.
  • Quote turnaround time for comparable submissions.

Review these measures together. Faster processing has limited value if reviewers must spend more time correcting the output. A lower referral rate may also be misleading if the workflow is missing legitimate escalation conditions.

Compare similar account types and investigate the reasons behind overrides. This helps separate useful automation from apparent efficiency that shifts work to another part of the process.

Frequently Asked Questions

What Is Agentic AI in Commercial Insurance Underwriting?

Agentic AI uses systems that coordinate multiple tasks toward an underwriting objective, such as preparing a submission for review. An agent can use approved information, tools, and configured rules to determine the next permitted step. Its access and authority remain controlled by the insurance organization.

How Is Agentic AI Different From Generative AI?

Generative AI creates or interprets information, such as a submission summary or referral draft. Agentic AI can use those capabilities as part of a sequence of actions. For example, it could identify that a summary is needed, prepare it, and route the account under approved workflow rules.

Will Agentic AI Replace Commercial Underwriters?

Agentic AI can take on administrative coordination, information gathering, and analysis preparation. Commercial underwriters remain responsible for the judgment and accountability assigned to their role, including complex risk assessment, exceptions, negotiation, and broker relationships. The division of work depends on the insurer's operating model and delegated authority.

Which Underwriting Workflows Are Best Suited to AI Agents?

Useful starting points include submission intake, completeness checks, appetite triage, risk enrichment, referral preparation, and renewal comparisons. The strongest candidates have a defined objective, reliable information, measurable outcomes, and clear escalation rules. Start where the workflow can be evaluated against an established human review process.

Does Agentic AI Mean Fully Autonomous Underwriting?

No. A workflow can allow an agent to gather information or route a submission while requiring human approval for consequential decisions. Autonomy can vary by task, line of business, and authority level. An insurer should define these boundaries explicitly and maintain a clear path for exceptions.

How Does Convr Support Agentic Underwriting?

Convr brings AI capabilities together with a commercial P&C data foundation and underwriting workflows. Its platform supports submission enrichment, proactive recommendations and actions, and access to risk information within a modular workbench. These capabilities help connect underwriting evidence with the work required to evaluate an account. Learn about Convr AI.

Modernize Commercial Underwriting With Convr

Agentic AI creates an opportunity to coordinate more of the work surrounding an underwriting decision. Its value depends on the quality of the information, the relevance of the insurance context, and the controls governing each action.

For carriers and MGAs, that means choosing technology that connects submission processing, risk intelligence, and workflow execution while keeping underwriters involved where their expertise is needed.

Convr's AI Underwriting Workbench brings these capabilities into a platform built for commercial P&C insurance. Teams can use it to structure fragmented submissions, surface relevant insights, and organize work around the accounts that need attention.

Book a demo with Convr to explore how its AI Underwriting Workbench can help your team reduce manual work, improve submission review, and take the next step in underwriting modernization.

‍

Realize End-to-End Underwriting Excellence with Convr AI

Experience how commercial P&C insurance organizations benefit from submission through quote with a frictionless process enriched by AI decisioning, empowering them to make better decisions, faster.