November 3, 2023
CASE STUDY
MMMM D, YYYY
xx min read

Predict Loss and Improve Pricing with Convr

There’s no doubt that to achieve profitability, commercial insurance companies must be accurate with their pricing. Forecasting future loss per exposure is critical for insurance carriers and reinsurers for pricing, but also producers and program managers to prioritize their efforts. 
 
In the practice of underwriting, selection and pricing require Olympic-level balance. If an insurance provider never writes any risks, they go out of business, however, if they write too many high-risk accounts without adequate premium, they become overexposed. The state of the art is to accurately forecast the frequency and severity of future losses, understand the uncertainty around these forecasts, and then use these to price insureds appropriately. Doing so brings in the right amount of revenue to accommodate the costs of claims and expenses. 
 
But there are other factors that come into play when pricing adequately, including: 
 

\n

  • Setting premiums high enough to adequately exceed total loss, and simultaneously low enough to be competitive and retain customers 
  • \n
  • Revising premiums often enough to reflect changing exposures and economic realities 
  • \n
  • Identifying exposures and risky conditions that can be mitigated by risk management initiatives 
     

\n

This is where predictive modeling comes in. Data science can be used to assess the risk profile of an insured to help set the right premium for their risk attributes. While many insurance providers have in-house actuaries or data scientists to build predictive models—Convr offers these modelers additional information, rich artificial intelligence (AI) features and risk scores to improve model accuracy. And the tools inside the Convr Underwriting Command Center bring an added layer of information and real-time insights to underwriters to directly improve the decision-making process.

\n

 
Sometimes using traditional methods that lean on historical loss data and policy level information—is not enough. Convr’s platform can help customers gain a competitive advantage in pricing through several available features. 
 
To aid insurers in this level of analysis, we’ve built: 
 

\n

Risk 360 AI™ where users can streamline their research and enhance applicant data with the power of AI. Risk 360 AI leverages Convr’s data lake—comprised of the digital footprint of millions of businesses—built with an underlying knowledge graph that unleashes detailed insights from the intersection of tens of thousands of data variables.

\n

Answers AI™ streamlines and centralizes all available information about an applicant’s business and answers underwriting questions directly through insurance trained AI models. There are two key components of d3 Answers: standardized questions to confirm or predict risk characteristics, and business classification. These answers can be included in an insurer’s pricing models and underwriting rules.

Intake AI™ eliminates manual submission processing by digitally ingesting, preparing and analyzing submissions. The product quickly extracts structured and unstructured data and applies AI to digitize data and assess accuracy. For every submission that flows through your business we extract key data points and enrich that information with third-party data to broaden and deepen the risk profile.

By automating and digitizing the insurance application process, underwriters use enhanced application data to quote faster, with more confidence. And they achieve more nuanced insights. There is no room for debate—greater accuracy and speed leads to better decisioning. And what provider does not want that?

All three of these products give the underwriter better information to modify the formulaic suggested premium. And they are better equipped to make more accurate pricing decisions—charging more or less based on the information provided through Convr.

And these capabilities apply to more than just single submissions. They can be used to evaluate entire books of business, rollover books of business and for bordereau ingestion.

So what are the benefits of better up-front risk awareness?

\n

  • Greater efficiency with a focus on better risks 
  • \n
  • More information to go into loss forecasting models 
  • \n
  • Better understanding of the appropriate premium for each risk 
  • \n
  • Providers are better able to compete for best risks 

\n

When models fail portfolio management
Another way Convr’s Risk 360 AI, Answers AI and Intake AI can be applied is when providers need to update their pricing models. Actuaries and data scientists at leading insurers need to experiment and test new modeling methodologies, model frameworks, and data sources regularly. Not updating models on routine cadence can result in models getting less and less accurate over time.

This is also true for the data that feeds models that price risks. Outdated data can lead to lost profits and cause better customers (those who are less risky) to leave their provider and poorer customers (those who present greater risk) to pay insufficient premiums. Outdated and/or insufficient data linked to insureds can also result in errors in risk management decisions, jeopardizing profitability or even solvency. Accuracy and current information is key.

\n

Here is a case when you don’t know what you don’t know! 
 
You can explore your out-of-the-box and customer modeling options at convr.com and reach out to Suzanne Vranicar at suzanne.vranicar@convr.com if you have any questions about the products and services listed. 

\n

blogs

Keep Reading

More articles on AI, underwriting and the future of commercial P&C.

XX MIN READ

The Hidden Cost of Manual Data Entry in Commercial Lines Underwriting

Ask a commercial lines insurance underwriting leader where their team's time goes, and the honest answer often isn't underwriting at all. It's data entry: keying in values from an SOV, cross-referencing a loss run against a submission, retyping limits and named insureds from a PDF into a rating system.

On paper, this looks like a minor operational cost, the price of doing business with documents that don't come in clean formats.  

The visible cost of manual data entry is time. A commercial property submission with a large SOV can take an underwriter or their support staff hours to process by hand, checking property values, occupancy types, and construction details against what's on the application. Multiply that across a full pipeline of submissions, and the hours add up fast.

While time is the cost that's easiest to see, it is often the least significant one. The hidden costs are the ones that don't show up until later.

‍The following are four hidden costs underwriting leaders need to consider:


Cost one: decision quality

Every hour an underwriter spends transcribing data is an hour not spent evaluating it. When manual entry eats into the day, the analysis that should happen around a submission -- spotting a concerning trend in loss history, questioning whether a stated property value is realistic, comparing an account against appetite -- gets compressed into whatever time is left.

Underwriting quality doesn't erode all at once. It erodes in small increments, submission by submission, as the ratio of time spent on data handling to time spent on judgment tips further out of balance. See why this is a hidden cost that cannot be overlooked?

Cost two: accuracy risk

Manual entry is also where errors creep in. A transposed limit, a missed COPE field, an incorrectly keyed TIV, these mistakes are easy to make and hard to catch, especially under volume pressure.

In commercial lines, where pricing and terms often hinge on the accuracy of property and exposure data, a small entry error can compound into a meaningfully mispriced risk. The cost of that error rarely surfaces immediately. It surfaces later, at claim time or renewal, when it's far more expensive to fix.

Cost three: inconsistent turnaround time

Manual processes don't scale evenly. When submission volume spikes, whether from a hard market, a new distribution partnership, or seasonal patterns, teams reliant on manual data entry hit a ceiling fast. Turnaround times stretch, brokers wait longer for quotes, and the accounts that move fastest aren't necessarily the best risks. In fact they're often the ones with the simplest paperwork. That's not a formula for disciplined underwriting; it's a formula for favoring ease over quality.  

Cost four: talent and turnover

There's also a cost that's harder to quantify but increasingly difficult to ignore: the toll manual entry takes on the people who are doing it.

Underwriters and underwriting assistants who spend a disproportionate share of their day on repetitive transcription rather than analysis tend to disengage from work that should be intellectually demanding. In a competitive labor market for underwriting talent, that's a retention risk hiding in plain sight.

Why this is solvable now

None of this is a new problem. What's changed is the availability of tools built specifically to solve it. Convr’s structured data ingestion, purpose-built for the ACORD forms, SOVs, and loss runs that make up commercial submissions, can take on the transcription work directly, pulling and validating data with a level of consistency manual entry can't match.

That data then feeds the Risk Context Engine, Convr’s ontology for commercial P&C risk, so a submission doesn’t sit as an orphaned record, it’s tied to the broader risk picture connected to prior submissions, relationships, and appetite history rather than evaluated on its own. That doesn't remove underwriters from the process. It removes the bottleneck standing between a submission arriving and a qualified underwriter evaluating it.

Rethinking where the real cost sits

The instinct to treat manual data entry as an operational cost is understandable.

It doesn't show up as a line item the way software or headcount does. But its true cost is distributed across decision quality, accuracy, turnaround times, and talent retention, all of which matter far more to a commercial lines book than the hours spent on submission entry alone.

The teams that recognize this are the ones rethinking where their underwriters' time really belongs, and building workflows that let judgment, not transcription, define how a submission gets handled.

If you’re ready for a conversation about re-envisioning how your team can improve the underwriting experience while avoiding some of these time sucking hidden costs, visit convr.com and book a demo today.

‍

XX MIN READ

Convr Prioritizes Communication in Underwriting Workbench

Email

Convr is making it easier than ever to communicate about submissions within the Convr AI Underwriting Workbench. Now there is an email capability where Convr customers can create new messages for submissions. A user would first need to have a specific submission open within the platform to see the email functionality available to them.

Within the left-hand pane they would just need to click, “Email” then “Create New Message.”

From there the “From” section will automatically be generated with their user email and they would need to plug in a recipient email address. The subject line would also be prepopulated with the submission name.

Convr users can also upload submissions assets and additional attachments about the submission in addition to crafting a customized message about the submission.

Comments
Within the Summary screen you can now also add a “Comment” about a submission, and they can be posted anywhere into Forms, Assets, Emails, etc. to support collaboration. Additionally, you can build a thread of comments. You can also reply to your own comment or react to another user’s comment with a thumbs up, as well.

The idea is that you’re creating a record or recorded conversation allowing another user to enter the platform, to get up to speed on the submission chat and join the conversation with the addition of new comments, which will show up within the feed as well.

You can tag users too, so they receive an in-app notification and email. You can also see in-app alerts, click on them and be taken directly to where you as a user were mentioned within the submission. This global, in-app notification feature is useful if a user wants to bring a team member’s attention to a given item within a submission.


The intent is to open lines of communication between underwriting team members to ensure there is greater transparency and oversight of submissions.

Convr is invested in improving the Convr AI Underwriting Workbench user interface for customers and believes these two new communication features will enhance collaboration and visibility throughout the submission process.  
 

To learn more about Emails and Comments capabilities reach out to Convr at convr.com to book a demo.

‍

XX MIN READ

Agentic AI Doesn’t Just Assist, It Acts

For most of its early history, the Artificial Intelligence (AI) that was used in commercial P&C insurance was a co-pilot. It was an always-on analyst sitting beside the underwriting team surfacing data, flagging anomalies, organizing submissions and more. It was genuinely valuable, yet it still relied on a human to make the call.

Agentic AI changes that equation entirely. It doesn't wait for a prompt or pass-back to a human for every decision. It perceives, reasons, decides, and acts autonomously, within defined parameters, at an unmatched speed and scale. With Agentic AI and the organizational shift from AI experimentation to real‑world execution, new challenges are emerging. If Agentic AI systems are making decisions and taking actions, insurance underwriting teams need to be ready. That means new roles and levels of authority need to be defined. That way, Agentic AI agents will operate within clear boundaries, stay anchored to trusted enterprise data, and scale confidently across the organization, so innovation accelerates without sacrificing governance and control.

The reason Agentic AI requires new operational control is specific to its potential independence of reasoning, decisioning and action. It’s collecting information and getting back to the underwriting team member(s) with a result or response. You're no longer just asking it a question, but giving it the autonomy to perform an action — giving it more authority to operate on your behalf.

When engaged via the Convr AI Underwriting Workbench, your organization benefits from the power of  this reasoning capability within an underwriting workflow. For example, it can act on your behalf sending emails back to a broker for more information. But better still, you benefit from the controls required to customize the workflows to your specific business and governance requirements.

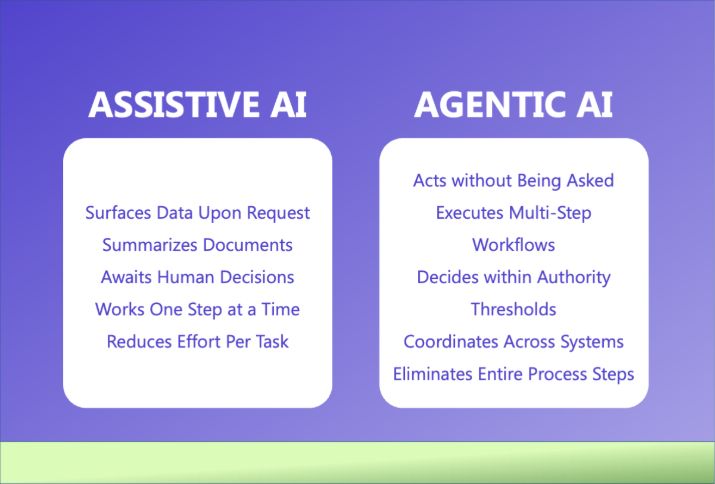
What separates Agentic AI from Assistive AI

Assistive AI is reactive. If you ask it a question, you’ll get an answer. If you feed it a commercial insurance underwriting submission, then you’ll get a summary. It’s powerful precisely because it reduces cognitive load — but the human remains in the loop at every decision point.

Agentic AI is proactive. It doesn't wait to be asked or given a prompt. Given a goal — clear a referral queue, flag a declination, prepare a financial analysis — an agentic system executes the full workflow: gathering relevant data, applying business logic, taking action, and reporting the outcome back to the underwriting team.

Here’s a helpful breakdown:


To learn more about Convr’s Agentic AI capabilities and what we’re doing for customers – get a demo now or read more about it on our newly revamped website at convr.com.


‍

Realize End-to-End Underwriting Excellence with Convr AI

Experience how commercial P&C insurance organizations benefit from submission through quote with a frictionless process enriched by AI decisioning, empowering them to make better decisions, faster.